Eldora: Town of Nederland Acquisition

The story is relatively straightforward

I would bet Eldora's financial results for winter 2025-26 fell below even the downside scenarios originally modeled to support the Nederland acquisition and proposed bond issue. We don't have the actual numbers, so that's speculation on my part, but the timing certainly raises the question. The financing was supposed to close this spring; the winter was disastrous, and the bonds still haven't been sold.

The basic problem with the model has always seemed pretty simple to me: Nederland needs enough Eldora operating cash flow to cover operations, ongoing capital investment, and debt service on a very large bond issue. A bad winter can hit that equation from both sides—lower revenue while many of the resort's operating and capital costs remain fixed.

And being part of Ikon does not necessarily provide Eldora with an insurance policy against a bad winter. Eldora is a partner resort, not an Alterra-owned resort collecting all of the Ikon pass revenue upfront. The critical question is how Eldora gets compensated under its confidential Ikon agreement. If compensation is driven by actual skier visits/scans, fewer skier days mean less Ikon revenue for Eldora.

Ski Area Management reports that Ikon scans can represent as much as 75% of Eldora's skier visits and describes the key economics as the “scan rate”—what Alterra pays Eldora for each Ikon Pass redemption. It also says preserving that scan rate is critical to the Nederland transaction.

A simple numerical example. If we assume Eldora typically sees roughly 400,000 skier visits annually and that 75% of those are Ikon pass holders, the math looks like this:

400,000 total visits × 75% = 300,000 Ikon scans

If Alterra reimburses Eldora $X per scan, then:

300,000 scans × $X = Eldora's Ikon access revenue

Now suppose a terrible snow year reduces those 300,000 Ikon visits to 225,000. Eldora has lost the reimbursement associated with 75,000 Ikon scans. Unless its confidential Alterra agreement contains a minimum guarantee or some other protection, that lost visitation translates directly into lost access revenue. I haven't found anything publicly establishing that such a guarantee exists.

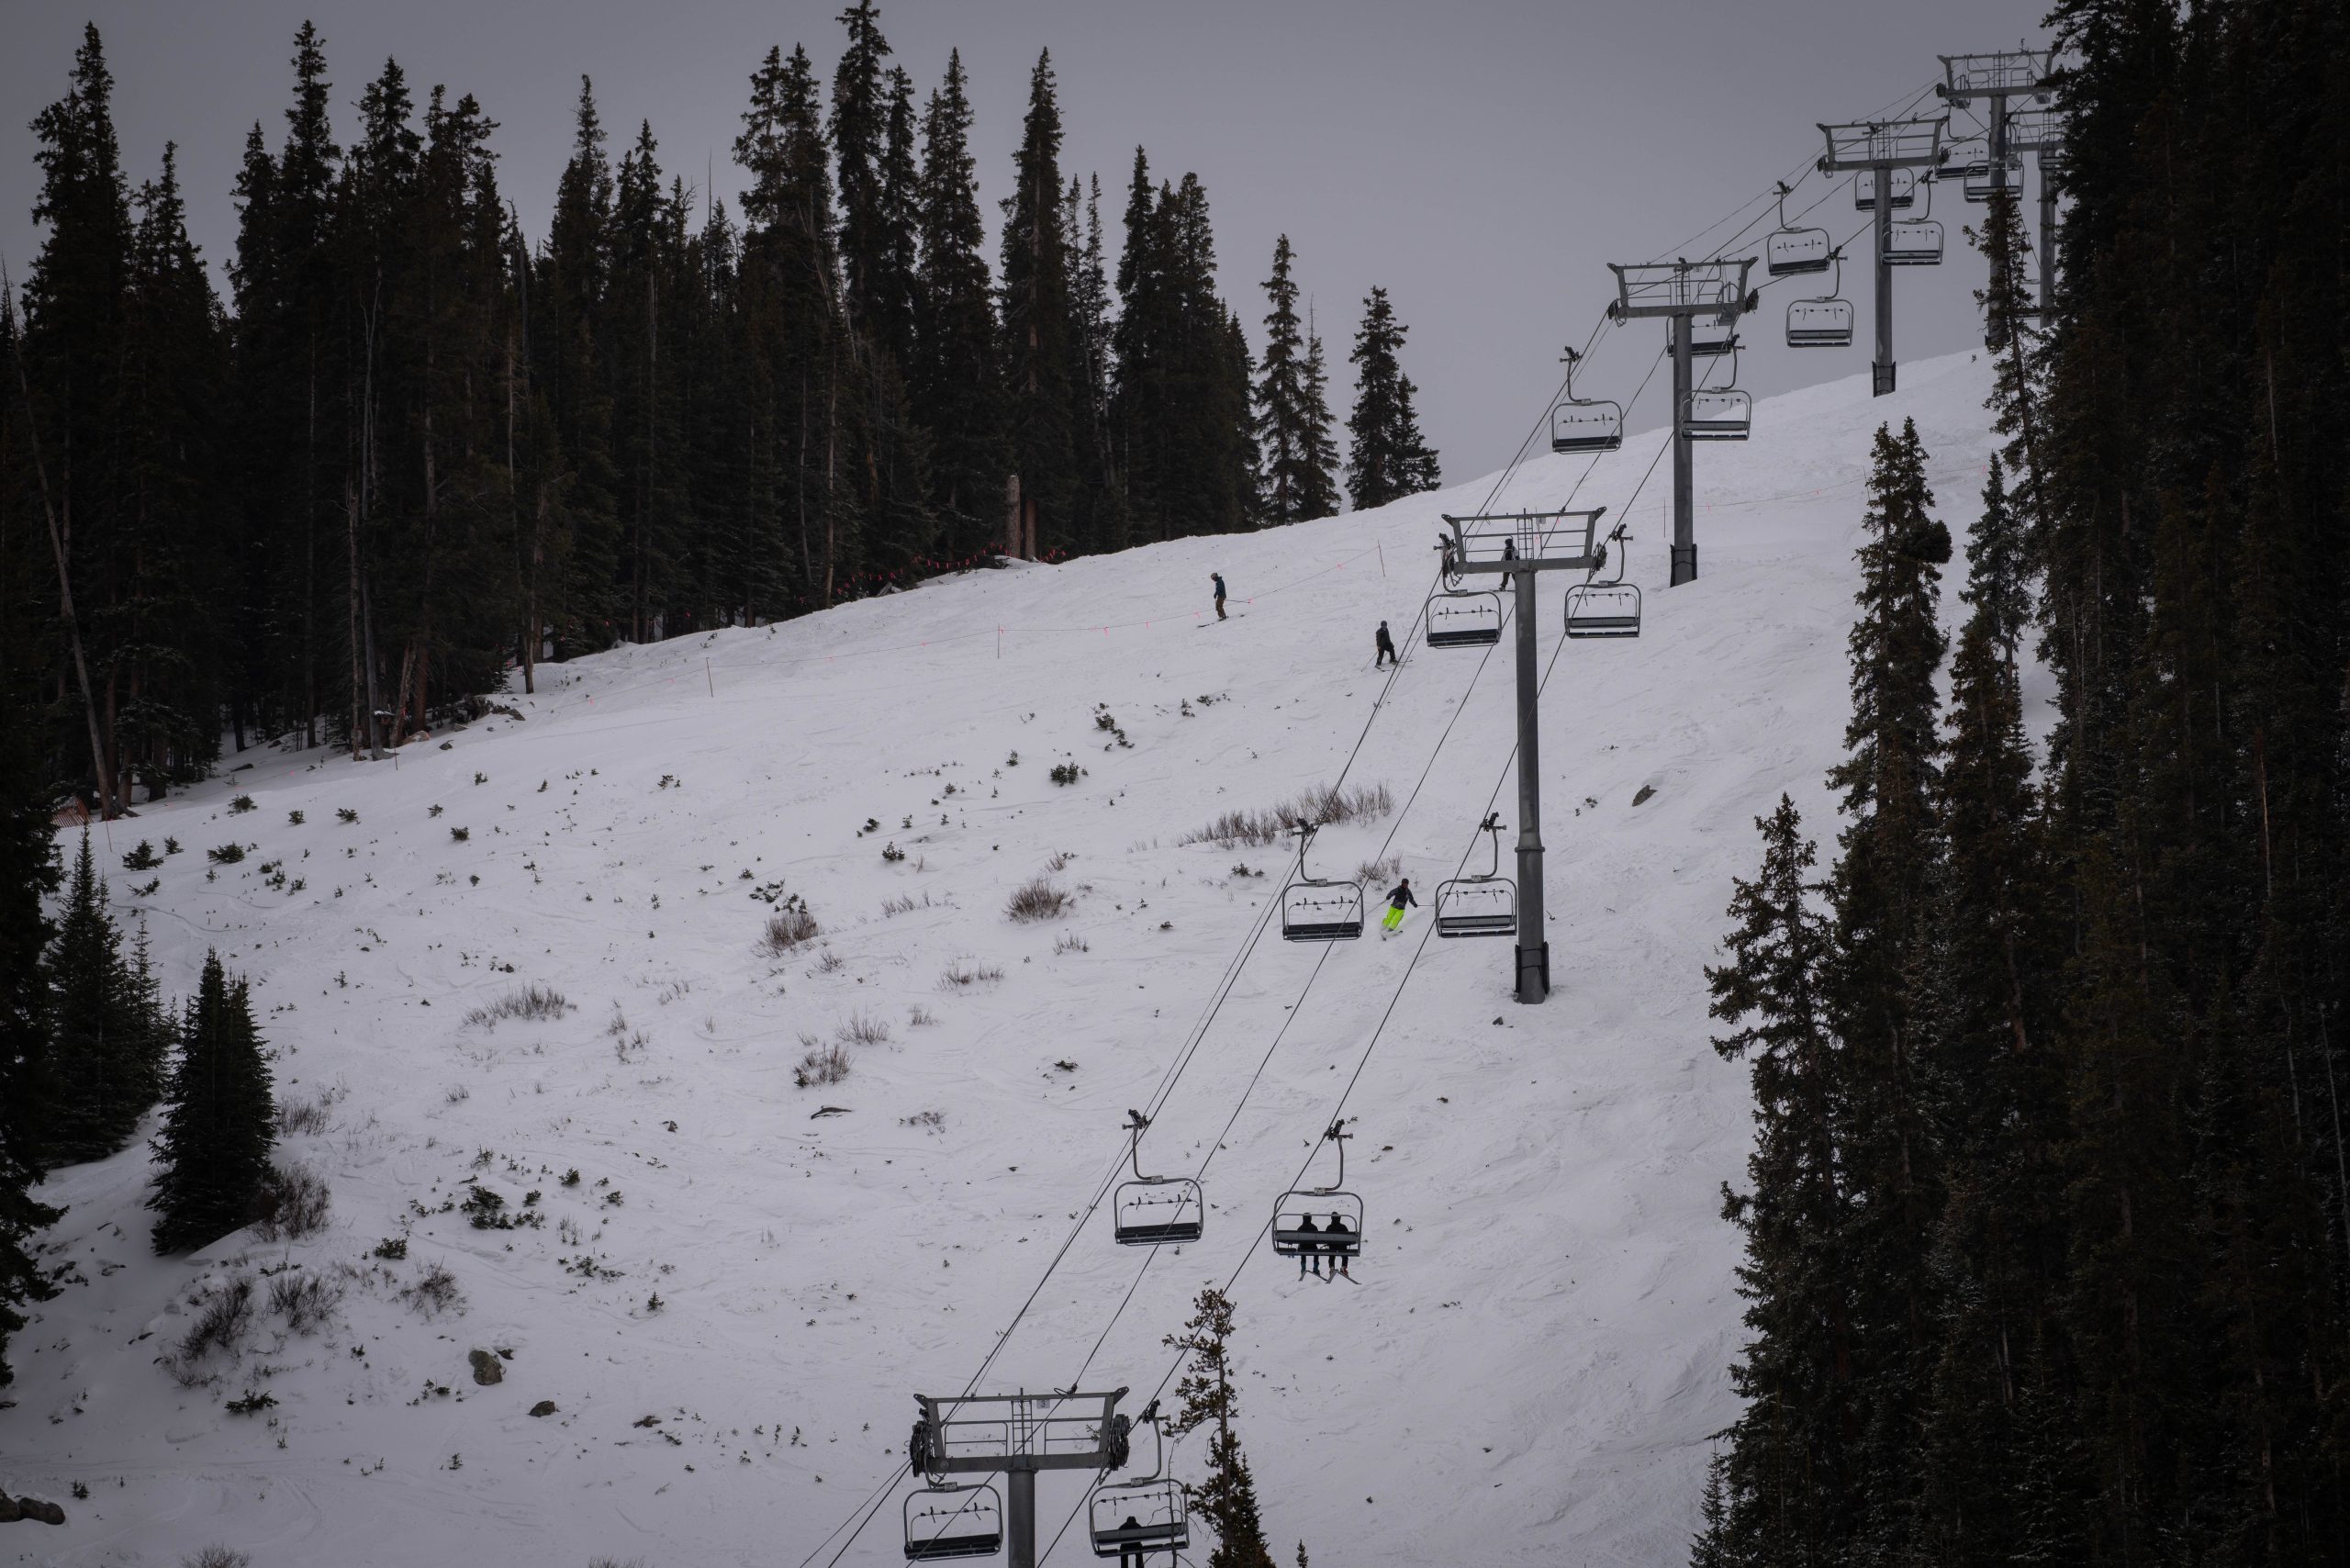
And that's why 2025-26 is particularly interesting for the bond deal. Colorado had an exceptionally poor early season, skier visits were down materially, and things got bad enough that Alterra actually offered some Ikon holders Mountain Credits to encourage them to ski in February.

Therefore: Ikon arguably makes Eldora more volume-dependent, not less. If roughly 75% of Eldora's visits are Ikon scans, a large portion of its access revenue depends on people physically showing up at Eldora.

Compare that with a traditional resort that sells a large percentage of its own season passes before winter. It has already banked that pass revenue whether the customer skis 30 days or three. Vail sells an Epic Pass in September and keeps that revenue regardless of how many times the passholder actually skis.

Eldora's Ikon arrangement appears fundamentally different. Ikon gives Eldora access to an enormous pool of Front Range customers, which is obviously extremely valuable. But if Eldora is predominantly compensated based on actual redemptions, Ikon isn't weather insurance. A bad snow year means fewer visits, fewer scans, and less revenue—while debt service doesn't change.

That becomes particularly important with leverage. A 20% decline in skier visits doesn't necessarily produce only a 20% decline in EBITDA. Snowmaking, lifts, insurance, maintenance, salaried labor, and much of the resort's infrastructure expenses don't disappear because visitation falls. Revenue can decline while much of the cost structure remains in place, causing EBITDA to fall much faster.

So, ironically, the disastrous winter of 2025-26 might ultimately benefit Eldora skiers. If one terrible season is enough to make the financing difficult or impossible, it exposes the financial risk critics worried about before Nederland takes on $120+ million of acquisition debt.


I'd much rather see this weakness exposed before the transaction closes than five years afterward, when a municipally owned Eldora could be forced to choose among higher prices, reduced operations, deferred capital investment, or additional borrowing to meet its obligations.
 
I tried to find any similar examples, and there really isn't one. Just some golf course acquisitions and hotels.

... beyond ski areas to utilities, hospitals, hotels/resorts, golf courses, broadband, real estate and other operating enterprises. The conclusion actually makes the Nederland–Eldora deal look more unusual, not less.

The important distinction is between a government buying infrastructure/property and a tiny municipality buying a going commercial business with employees, customers, operating risk and competitive revenue...
Nederland's annual town budget is only a little over $3 million, versus a $120 million Eldora purchase. The town manager memorably characterized it as essentially a "minnow swallowing a whale."


Mt. Ashland, Oregon, is perhaps the most relevant point of comparison.

In 1992, the community's “Save Mt. Ashland” campaign raised about $1.7 million to acquire and preserve the ski area; contemporary accounts put the required purchase price at about $1.3 million, with $500,000 coming from Oregon state lottery/economic-development funding. The City of Ashland served as the vehicle for the acquisition and held the Forest Service permit, while the newly created nonprofit Mt. Ashland Association operated the mountain.
In terms of skier days, Mt. Ashland is roughly a 100,000-visits-per-year mountain. The City of Ashland describes normal visitation as over 100,000 annually. Recent examples were 95,944 visits in 2023–24, roughly 114,000 in 2024–25, and a record 128,625 in 2022–23. Ashland, Oregon

So for your Eldora comparison:
Mt. Ashland: ~$1.3–1.7M rescue acquisition → ~100K skier visits/year

Eldora: $120M proposed acquisition → ~400K skier visits/year
Eldora therefore has only about 4× the skier visits but roughly 70–90× the acquisition cost.
 
Can confirm a few details.

Yes skier visits have risen under Powd'r Corp to roughly 400K. Have not heard for last year though and has to be significantly fewer.

Can also confirm that the current Eldora-Ikon deal is a per skier day payment. No minimums or guarantees. Eldora goes out of its way to try to talk skiers into showing up for only a couple hours either morning or afternoon to try to increase Ikon scans relative to parking lot issues or just getting some more scans midweek even if only for a few lift rides.

As I have repeated. Ned is the only one stupid enough to either offer $120M for Eldora OR to plan to borrow 100% of the cost of acquisition with no other capital involved.
 
Oh brother.

Town of Ned is now begging the State of Colo and others to help them fund the acquisition.

Den Biz Journal

Story Highlights​

What's This?
  • Nederland town officials urgently sought state funding to close a financing gap on the $120 million Eldora acquisition, email show.
  • Powdr Corp. recently sought a quick answer from Nederland how it would fill the gap or the company would relist the mountain.
  • Nederland plans to finance the ski resort purchase through municipal bonds backed by Eldora's earnings, not town tax dollars.
 
As I have repeated. Ned is the only one stupid enough to either offer $120M for Eldora OR to plan to borrow 100% of the cost of acquisition with no other capital involved.

Some interesting background information:
  • 2023: POWDR decides to partially exit → packages five mountains → Alterra agrees to buy the package → deal fails in due diligence. SAM Magazine
  • 2024: Alterra separately buys A-Basin for ~$105M and undergoes DOJ review.
  • 2024–26: POWDR sells/markets its resorts individually.

For Eldora specifically, antitrust is another major factor.

The DOJ scrutinized Alterra's $105M A-Basin acquisition, and The Colorado Sun reported that the federal review likely contributed to Alterra and Vail's apparent lack of interest in subsequently buying Eldora.

So there was not that much competition for Eldora - maybe Boyne if the price was right?


The sale price was not completely out of line. Important note: A-Basin has a below-average 2023, so the comps are a bit off.


1790689622841.png
 
So there was not that much competition for Eldora - maybe Boyne if the price was right?
They were the most interested private buyer is what I heard.

One could see other players perhaps being interested in a toehold in the Colo Front range market too (maybe MCP, Pacific Capital, Invision Capital), but only Ned willing to go for max price at 100% debt financing.

But I agree that both Alterra and Vail would have a tougher time getting past the DOJ for anti-trust even with Trump admin in place.

Latest rumor is that mayor of Ned will send out some sort of press release at 5p today.
 
but only Ned willing to go for max price at 100% debt financing.

This is the problem.


I am sure Winter 2025-26 destroyed the business case for Eldora's purchase by Nederland CO for the bonds and 100% financing. Eldora's normal 400k visits, Ikon pass reimbursements, and EBITDA declined to levels no one considered. A bad winter can mean a 5-10% decline.

No one would ever model Colorado's skier days retreating to 1990s levels, down 24%. Vail can survive this due to its Epic Pass product. An Eldora 100% debt-financed acquisition cannot.

Colorado Skier Days 2025-26: Collapse 24%, Lowest Since 1991-92

​


1790799801324.png


Debt Service and Coverage Ratios

That matters because EBITDA has to support debt service. If Nederland ultimately borrowed $200 million over 40 years, approximate level annual principal-and-interest payments would be about $13.3M at 6%, $15.0M at 7%, $16.8M at 8%, and $18.7M at 9%. At the full $225 million authorization, those figures rise to roughly $15.0M, $16.9M, $18.9M and $21.1M, respectively. The ordinance allows maturities as long as 40 years and sets 9% as the maximum net effective interest rate. The actual amortization could be structured differently, so these are illustrations rather than Nederland's projected debt-service schedule.

Here's why DSCR—debt-service coverage ratio—is the number to watch. If a resort has $20M available for debt service and owes $15M annually, its coverage is 1.33×. A 1.50× ratio would require $22.5M of cash available to cover that same $15M payment; 2.0× requires $30M. And EBITDA itself can overstate the real cushion because Eldora still has to fund recurring lift, snowmaking, grooming, building and other maintenance capital. Nederland's ordinance explicitly anticipates capital-maintenance and capital-expenditure funds, as well as debt-service and operating reserves.

Illustrative scenario$200M debt$225M debt
Annual debt service @ 6%$13.3M$15.0M
@ 7%$15.0M$16.9M
@ 8%$16.8M$18.9M
@ 9% maximum$18.7M$21.1M
Cash needed @ 1.50× coverage, 8%$25.2M$28.4M
Cash needed @ 1.50× coverage, 9%$28.1M$31.6M

So if Eldora's normalized EBITDA really were only $15–20M, financing anything close to $200–225M of fully amortizing debt at high-single-digit yields would look extremely tight under a simple level-debt model. At $20M EBITDA and $200M borrowed at 8%, EBITDA/debt service would be only about 1.19× before maintenance capex. At $225M and 8%, it would be only about 1.06×. That doesn't prove the transaction cannot work—the actual issue could be smaller, amortization could be back-loaded, capitalized interest/reserves can change early-year coverage, and the confidential financials could show materially higher cash flow—but it demonstrates why the undisclosed EBITDA and final bond structure matter so much.


So if 2025–26 Eldora EBITDA dropped materially, the debt-service coverage ratio could have deteriorated very quickly.

For example, if annual debt service were $11M:

Eldora cash flow available for debtDSCR
$18M1.64×
$15M1.36×
$13M1.18×
$11M1.00×
$9M0.82×

​


Nederland has authorization to issue up to $225 million. That is not the same thing as having $225 million of financing committed.

The ordinance says BofA Securities and RBC Capital Markets will purchase/sell the bonds on a “best-efforts basis.” It also permits them instead to act as placement agents for privately placed portions of the issue. The bonds are restricted to institutional accredited investors and qualified institutional buyers.

In other words:

BofA/RBC are trying to find sophisticated investors willing to buy the debt. They are not, based on the public ordinance, guaranteeing that their own balance sheets will fund the entire $225M if investors won't buy it.

Nederland itself acknowledges that the acquisition and related financing may not close.

​


Market Interest Rate

Nederland has authorized the bonds at a maximum 9% net effective interest rate. But the actual rate isn't something Nederland simply chooses. BofA and RBC have to discover the yield at which institutional investors will accept Eldora's business risk.

If investors are comfortable at 6–7%, debt service is considerably easier. If investors demand 8–9%, that both raises annual debt service and suggests investors perceive substantially greater credit risk. If sufficient investors demand more than 9%, Nederland hits the ordinance's present ceiling. It would then need some combination of a smaller bond issue, different structure/security, additional capital, changed economics or further Board authorization rather than simply selling the currently authorized bonds above 9%.
 
Last edited:
How does Eldora have twice the revenue of A-Basin with 2/3 the skier visits?

The A-Basin data is from FY 2023. Bad winter, bad revenue/results, but actuals.

600k was almost peak Vail relationship... AI crap.


A-Basin vs. Eldora skier visits over time​

Season / periodArapahoe BasinEldoraNotes
Mid/late 1990s~215K–263K~175KEldora historical average
2001–02151,678—Terrible A-Basin snow year
2002–03317,401~170K–200K avg.A-Basin adds snowmaking
2003–04275,428—
2004–05328,251—
2005–06326,166–326,428—
2002–12 average~354,300~271,000 10-yr avg.Master-plan figures
2013–14 era~350K–400K range~300K–375K rangeEldora range less authoritative
2018–19Peak / ~500K+ range—A-Basin's final Epic season
2019–20~39% lower initially after leaving Epic—A-Basin intentionally reduced crowds
2021–22~lower-400K range*~400K range*approximate
2022–23~75% of 2018–19~400K+ range*A-Basin +9% YoY through Apr.
2023–24~400K-ish*~400K+*public exact totals scarce
2024–25~400K-ish*400K+ reported
2025–26TBD / likely materially lowerTBDColorado overall −24%
 
Since the veil of secrecy came down around 2010 or so, it has become very difficult to find individual area skier visit stats. Stuart invested a lot of time chasing down everything he could find for skier visit history.

2011-12 was the last year he has for A-Basin, a year rather similar to this one in Colorado, with 285K visits down from the then record high 453K in 2010-11. The last year Stuart has for Eldora is 287K in 2009-10.

Stuart occasionally dug up skier visit data from master plan filings for expansions. It's possible A-Basin had to disclose skier visits for the Alterra purchase and similarly Eldora in its current situation.
 
Eldora's recent information is from a SAM article.


Eldora metric SAM reported figure
Annual skier visits 400,000+
Annual revenue ~$50M
EBITDA margin >20% consistently
Implied normal EBITDA >$10M
Ikon share of visits as much as 75%
Purchase price $115–120M


A-Basin's information is from financial filings and news reporting:


1790803752906.png


Skier days~600,000 .....Dream's Feb. 2024 sale announcement says skier days grew from under 200K to “about 600,000” during its ownership. It does not specify that 600K was the most recent season.

The 600,000 figure comes directly from Dream Unlimited, A-Basin's seller, in its February 5, 2024 announcement of the sale to Alterra. This is the primary source. Dream CA
Dream says:
“During Dream’s ownership, the management team increased skier days from under 200,000 skiers to about 600,000 skiers...” Dream CA

Dream Unlimited — A-Basin sale announcement
SAM subsequently repeated the same figure, saying skier visits increased from fewer than 200,000 to about 600,000 after Dream acquired A-Basin in 1997.
 
Last edited:
I don't have exact figures, but know that the Eldora number in recent seasons was running at "roughly 400K". But that was prior to last years terrible year. No idea what % drop they had but it was probably similar to the rest of Colo.

I also know from an insider that prior ownership at Eldora used to report totally fake skier numbers to CSCUSA (the trade group that used to report them). So it is much more of an unknown just what visits were from the 00's and 10's.
 
Denver Business Journal ran article today....

“Newly obtained emails show Nederland officials begging for forgiveness while asking for state funds to buy the ski area. "We thought we would have more time."

Please reach out to the Governor's office and voice your opinion. This deal needs to die now, we simply can't have these officials attempting to run Eldora. This whole exercise by Nederland has been a trainwreck and needs to be killed.
 
“Newly obtained emails show Nederland officials begging for forgiveness while asking for state funds to buy the ski area. "We thought we would have more time."

No, they don't need more time.


Winter 2025-26 appears to have exposed the fundamental weakness in the financing.

The entire deal depends on Eldora generating enough cash to operate the mountain, fund necessary capital investment, and service the acquisition debt. After a disastrous winter, Nederland is now seeking state assistance to close a financing gap. That strongly suggests the economics don't work on the terms originally contemplated.

Investors have also now seen firsthand how volatile Eldora's cash flow can be. Ikon doesn't necessarily insure Eldora against a bad season—if reimbursement is primarily based on skier scans, fewer visits mean less revenue. Meanwhile, debt service remains fixed.

The result is pretty straightforward: lower operating cash flow + higher required borrowing costs = weaker debt-service coverage. If the bonds could be sold in sufficient quantity at an interest rate Eldora's cash flow could comfortably support, Nederland wouldn't need outside money to reduce the financing requirement.

The problem isn't time. The problem is the numbers. Winter 2025-26 gave prospective bond investors a real-world stress test of the business model, and the deal still hasn't been financed.
 
Assume Powdr had had enough of the Netherlands' local government.

Sell it to Boyne or the following:

One could see other players perhaps being interested in a toehold in the Colo Front range market too (maybe MCP, Pacific Capital, Invision Capital), but only Ned willing to go for max price at 100% debt financing.


Eldora just seems to have become a local asset to Front Range skiers. At one point, it was not well run - 80s/90s? Old lifts, windy, low snowfall, and poor snowmaking. Why go back in time?
 
Back
Top